


By mindnesto Editorial Team · Updated June 2026 · 10 min read
Reviewed for medical accuracy — sources cited from APA 2024, LifeStance Health July 2026, Bank of America 2025, Financial Finesse 2026, Frontiers in Public Health 2026 and peer-reviewed clinical research
You open your banking app. Your heart rate spikes. Your stomach drops. You close it before the numbers fully load — not because you do not care about your finances, but because checking them feels genuinely dangerous.
Or perhaps it is subtler than that. A low-grade hum of dread that never quite goes away. The inability to enjoy a meal out without mentally calculating what it costs. Lying awake at 3am running numbers that never seem to add up regardless of how many times you run them. Feeling vaguely ashamed of your financial situation even when, objectively, you know things are not catastrophic.
Financial stress is one of the most consistent triggers of anxiety and depressive symptoms in adults. The American Psychological Association’s 2024 Stress in America survey found that 73% of respondents rated the economy as a significant source of stress — the second most common stressor in the country. A separate national survey found that at least 4 in 5 Americans — 83% — report financial stress driven by inflation, rising living costs, and recession fears.
If you are experiencing financial anxiety, you are not alone. You are not bad with money. And you are not failing at adulthood. You are experiencing a physiological response — one that is completely explainable by neuroscience, completely understandable given the economic environment of 2026, and completely addressable with the right strategies.
This guide covers the complete picture — what financial anxiety actually is, what the 2026 data tells us about its scale and causes, the neuroscience behind why money worries feel so physically threatening, and 10 evidence-based strategies that genuinely interrupt the cycle.
We have connected this to our stress management guide, our anxiety journaling prompts, and our guide on can money buy happiness — because financial anxiety, stress, and the relationship between money and wellbeing are deeply interconnected systems.
⚠️ Medical Disclaimer: This article is for informational and educational purposes only. Persistent financial anxiety that significantly affects your daily functioning, sleep, or relationships warrants professional support. Please speak with your GP or a qualified mental health professional.
What Is Financial Anxiety — The Clinical Picture
Financial anxiety is a persistent pattern of excessive worry, fear, and avoidance centred on money — including income, spending, debt, savings, and financial security. It is not simply being concerned about a genuinely difficult financial situation. Financial anxiety involves a disproportionate and often uncontrollable level of distress that persists even when the objective financial picture does not warrant it — and that significantly impairs daily functioning.
The convergence of economic pressure and mental health strain — what LifeStance Health coins “stressflation” in its 2025 survey of 1,026 US adults — creates a cruel paradox: the same financial pressure fuelling the distress is also keeping people from getting support. 60% of respondents have avoided seeking mental healthcare because of financial constraints.
Financial anxiety exists on a spectrum. At one end, it is a rational and proportionate concern about a genuine financial difficulty. At the other, it is a clinically significant anxiety pattern that distorts perception, impairs decision-making, and produces physical symptoms entirely independent of the objective financial situation.
Money Dysmorphia — The 2026 Term Everyone Needs to Know
One of the most significant 2026 developments in financial mental health is the increasing clinical recognition of money dysmorphia — a pattern in which a person’s perception of their financial situation is significantly distorted relative to their actual circumstances.
The Credit Karma survey found that 29% of Americans experience money dysmorphia, with the rate climbing to 43% among Gen Z and 41% among millennials, compared to 25% among Gen X and 14% among adults 59 and older. Among those who experience it, 95% say it negatively impacts their finances — holding them back from saving, pushing them toward overspending, or driving them into avoidable debt.
Money dysmorphia is not a formally recognised clinical diagnosis — but the pattern it describes parallels the cognitive distortions seen in other anxiety and mood presentations. It can manifest as persistent financial insecurity despite objective financial stability, catastrophic thinking about minor financial setbacks, or an inability to derive satisfaction from financial achievements regardless of their scale.
Social media comparison — constant exposure to curated wealth on platforms like TikTok and Instagram — may distort the baseline of what financial success looks like, particularly for younger adults.
The 2026 Financial Anxiety Crisis — What the Data Shows
Beyond the rising cost of rent and groceries, adults in 2026 are paying an “invisible tax” on their mental health. Managing a digital economy requires a high degree of cognitive labour — from tracking dozens of automated subscriptions to the constant fear of identity theft and the pressure of “side-hustle culture.” Every notification — a PayPal alert, a Venmo request, a subscription renewal — acts as a tiny withdrawal from your emotional bank account. Over time, this leads to chronic irritability and the “scattered” feeling often associated with burnout.
This invisible digital tax is a 2026-specific financial anxiety driver that no prior research fully captured. The cognitive load of managing a digital financial life — with its subscriptions, automated payments, algorithmic price changes, and constant comparison signals from social media — creates a chronic background hum of financial vigilance that depletes the prefrontal cortex resources needed for calm, rational financial decision-making.
The Neuroscience of Financial Anxiety — Why Money Worries Feel Physical
This is the section that removes the shame from financial anxiety entirely — because understanding what is happening in your brain when money anxiety activates makes the response feel completely logical rather than embarrassing.
The Amygdala Cannot Tell the Difference Between a Debt and a Predator
The brain interprets unpredictable financial demands much like other survival threats — activating the sympathetic nervous system and keeping cortisol levels elevated. Bills arrive on a schedule, but income often does not.
Your amygdala — the brain’s threat detection system — evolved in an environment where the primary threats were physical: predators, rivals, starvation. It processes the threat of financial insecurity through exactly the same neural circuitry it uses for physical danger — because social and resource-based threats are neurologically processed as survival threats.
When you check your bank balance and it is lower than you need, your amygdala fires. Cortisol spikes. Adrenaline activates. Your heart rate elevates. Your muscles tense. You experience the full physiological profile of a threat response — and this is why financial anxiety feels so physically exhausting. You are not catastrophising. You are running a survival response multiple times per day.
Cortisol, HPA Axis, and the Financial Stress Feedback Loop
In the long term — sustained over months or years of financial uncertainty — the stress response becomes pathological. Chronically elevated cortisol is associated with impaired immune function, elevated inflammatory markers, disrupted sleep architecture, increased visceral fat accumulation, and elevated cardiovascular disease risk.
Dr. Bruce McEwen of Rockefeller University identified the cumulative biological cost of this sustained activation as allostatic load — measurable physiological damage that accumulates when the HPA axis cannot return to baseline between stressors. Financial anxiety is one of the most consistent producers of allostatic load in modern adult life — because unlike most physical threats, money worries are available 24 hours per day and are not resolved by the fight-or-flight response that evolved to address them.
The Financial Planning Association’s Journal documented in November 2025 that financial stress creates a feedback loop in which poor health further strains financial resources. The loop, once established, is self-reinforcing: financial stress generates health costs, which create more financial stress, which generates more health costs.
The Scarcity Mindset and Tunneling — How Financial Anxiety Impairs Decision-Making
Professor Sendhil Mullainathan of Harvard University and Professor Eldar Shafir of Princeton University — in their landmark research on scarcity psychology — identified tunneling as one of the most important cognitive consequences of financial anxiety.
Tunneling describes the amygdala-driven narrowing of attention toward the immediate financial threat — the bill, the debt, the empty account — at the direct expense of longer-term planning, creative problem-solving, and the broader perspective needed for sound financial decision-making. When tunneling, the brain is not simply stressed. Its prefrontal cortex bandwidth — the cognitive resource responsible for planning, impulse control, and rational assessment — is measurably reduced.
The traditional advice for financial stress is to make a budget. However, you cannot make a sound financial decision while your body is in fight-or-flight. This is the reason that much standard financial advice is ineffective for people with significant financial anxiety — it assumes a neurological state of calm deliberation that financial anxiety actively prevents. Before budgeting is possible, the nervous system must be regulated enough to allow prefrontal cortex access.
Financial Trauma — When Childhood Money Experiences Leave a Lasting Imprint
For many people, financial fear is connected to earlier emotional experiences. Children are highly sensitive to the emotional atmosphere surrounding money. Even when parents attempted to hide financial stress, children often absorbed it — and scarcity-based thinking often creates a nervous system state of chronic anticipation.
Financial trauma — the lasting neurological imprint of growing up in an environment where money was scarce, conflict-laden, or unpredictable — can produce financial anxiety in adulthood that persists even after the objective financial circumstances have dramatically improved. The amygdala’s threat associations with money-related stimuli, formed in early childhood, do not automatically update when the bank balance does.
Understanding whether your financial anxiety has a trauma component — rather than simply a current-circumstances component — significantly shapes which interventions will be most effective.
The Signs of Financial Anxiety — Recognising the Full Pattern
Financial anxiety shows up differently for different people — and recognising your specific pattern is the first step toward addressing it effectively.
Anxious Financial Patterns
- Obsessively checking bank accounts and financial apps — multiple times per day despite the checking never providing lasting reassurance
- Avoiding opening bills, bank statements, or financial correspondence entirely — because the anticipated distress feels worse than the uncertainty
- Catastrophising minor financial setbacks as evidence of impending financial ruin
- Difficulty spending money on genuine necessities because the spending itself triggers anxiety
- Constant mental calculation of every expense — inability to enjoy purchases without immediate regret
- Physical symptoms when confronted with financial information — racing heart, shortness of breath, nausea, dizziness
Depressive Financial Patterns
Financial stress often forces a withdrawal from the activities, social events, and self-care routines that protect mood — removing the buffers that normally guard against depression. In a culture that often equates financial success with personal value, persistent money problems may be internalised as evidence of personal failure — a known cognitive driver of depressive episodes.
Depressive financial patterns include losing interest in activities previously enjoyed because of financial concerns, social withdrawal driven by the shame of financial difficulty, pervasive hopelessness about financial improvement regardless of objective circumstances, and the learned helplessness that develops when sustained financial effort appears to produce no meaningful change.
Avoidance Patterns
Avoidance is one of the most common and most damaging financial anxiety presentations — because it provides short-term relief at the cost of worsening the underlying situation. Avoiding opening post, avoiding checking accounts, avoiding financial conversations with partners, and avoiding professional financial advice all feel protective in the moment and compound the anxiety over time.
10 Evidence-Based Strategies to Manage Financial Anxiety
1. Regulate Your Nervous System Before Making Financial Decisions
Given the tunneling and prefrontal cortex suppression that financial anxiety produces, the most important practical principle is this: never make significant financial decisions — or attempt to create a budget, review statements, or have a financial conversation with a partner — while in an acute anxiety state.
Before any financial engagement, spend five minutes using extended-exhale breathing — four counts in, six counts out — to activate the parasympathetic nervous system and restore prefrontal cortex access. This is not avoidance. It is the neuroscience-informed prerequisite for sound financial engagement.
2. Separate Financial Facts From Financial Fears
One of the most consistently effective CBT techniques for financial anxiety is creating a clear, written distinction between financial facts — the actual numbers, the actual obligations, the actual income — and financial fears — the catastrophic projections, the worst-case scenarios, the shame-laden narratives.
Financial facts can be assessed, planned around, and addressed. Financial fears cannot — because they exist in imagination, not reality. Write both lists. Notice how often the fear list is significantly more distressing than the fact list. The gap between them is where financial anxiety lives — and naming it is the beginning of reducing it.
3. Schedule Financial Engagement Time
Rather than having financial anxiety intrude continuously throughout every day, scheduled financial engagement — a specific, time-limited window for checking accounts, reviewing budgets, and processing financial information — contains the behaviour within a managed boundary.
Choose 20 to 30 minutes at a specific time, ideally mid-morning when cortisol is naturally lower. During this window, engage fully with your financial reality. Outside this window, when financial anxiety thoughts arise, deliberately postpone them: “I acknowledge this concern. I will give it my full attention at 10am tomorrow.” Our anxiety journaling prompts include specific financial worry externalisation prompts that support this practice.
4. Address the Avoidance Pattern Directly
Because avoidance worsens financial anxiety by allowing feared financial information to accumulate unchecked, addressing it through graduated exposure is one of the most important interventions available. Start with the least feared financial task — perhaps simply checking one account balance — and complete it with your nervous system regulated. Notice that the anticipatory anxiety was worse than the actual experience. Build gradually toward the more avoided behaviours — opening unopened correspondence, reviewing a full bank statement, checking the total debt figure.
Each exposure reduces the amygdala’s threat association with financial information — progressively making financial engagement feel less physiologically dangerous.
5. Practise Intolerance of Uncertainty Reduction
Financial anxiety is fundamentally driven by intolerance of uncertainty — the belief that financial uncertainty itself is dangerous and must be resolved through continuous monitoring and worst-case planning. Since financial life is irreducibly uncertain, this strategy is guaranteed to maintain anxiety indefinitely.
Graduated exposure to financial uncertainty involves deliberately refraining from reassurance-seeking behaviours — checking accounts, running financial calculations, seeking reassurance from partners — and discovering that the uncertainty does not produce the catastrophe the anxiety predicts. This builds the capacity for genuine financial peace that constant monitoring never provides. Our guide on how to stop overthinking covers the intolerance of uncertainty framework in depth.
6. Use Cognitive Reappraisal for Financial Catastrophising
When financial catastrophising arises — the mental projection from “I am behind on this bill” to “I am going to lose everything” — apply the cognitive reappraisal sequence:
Step 1: Identify the catastrophic thought precisely: “I am going to end up unable to pay my rent.”
Step 2: Identify the evidence for and against this prediction based on actual facts rather than feelings.
Step 3: Generate three realistic alternative outcomes between the current situation and the worst case.
Step 4: Ask: “If a close friend described this situation to me, what would I realistically say to them?”
This sequence activates the prefrontal cortex and reduces amygdala-driven catastrophising — producing a more accurate and less distressing assessment of the actual financial situation.
7. Address Financial Trauma With Professional Support
If your financial anxiety has a significant trauma component — if money-related anxiety feels disproportionate to your current circumstances, if it began in childhood, or if it triggers responses that feel more like survival than rational concern — professional therapeutic support produces the most complete and lasting outcomes.
CBT, EMDR (for financial trauma specifically), and schema therapy all address the early financial experiences that shaped the amygdala’s threat associations with money. Resolving these at the root level produces financial anxiety relief that budgeting and financial planning alone cannot achieve.
8. Protect Sleep From Financial Rumination Specifically
Sustained cortisol elevation and disrupted sleep are independent risk factors for depression — and financial stress often produces both. Financial rumination is one of the most consistent drivers of nighttime wakefulness — because the absence of daytime distraction allows the amygdala’s financial threat monitoring to dominate awareness.
Pre-sleep worry journaling — writing every financial concern and the next action for each one — externalises cognitive content before the sleep window, preventing nocturnal financial rumination. Our sleep hygiene guide provides the complete protocol for protecting sleep from anxiety-driven rumination.
9. Build Financial Connection — Not Just Financial Planning
One of the most underrecognised financial anxiety interventions is reducing the shame and isolation that financial difficulty produces — through genuine conversation with trusted people about money. Financial anxiety thrives in silence and comparison. It weakens in honest, non-judgmental human conversation.
This does not mean sharing sensitive financial details indiscriminately. It means finding at least one trusted relationship — a partner, a close friend, a financial counsellor — in which financial reality can be discussed honestly. The social buffering of financial stress — even brief genuine human contact about shared financial concerns — activates oxytocin and directly counteracts cortisol.
10. Access Free Financial Wellbeing Support
Professional financial guidance — not just mental health support — is an underused financial anxiety resource in all four Tier 1 countries. Free, confidential financial counselling is available specifically to reduce the practical uncertainty that drives financial anxiety.
Financial support by country:
- UK: MoneyHelper — free financial guidance | StepChange Debt Charity — free debt advice | Citizens Advice
- USA: National Foundation for Credit Counselling (NFCC) | CFPB financial tools
- Canada: Credit Counselling Canada
- Australia: National Debt Helpline — 1800 007 007 (free)
Mental health support:
- UK: NHS Talking Therapies | Mind — Money and Mental Health
- USA: ADAA Therapist Finder | SAMHSA Helpline — 1-800-662-4357
- Canada: CAMH
- Australia: Beyond Blue — 1300 22 4636
Financial Anxiety Key Takeaways — Featured Snippet Optimised
The complete 2026 evidence-based summary:
- 83% of Americans report financial stress as of July 2026 — the second most common stressor after work
- Money dysmorphia affects 29% of Americans — rising to 43% of Gen Z — distorting perception of financial reality independent of actual circumstances
- 66% of employees are financially stressed, with 76% believing costs are outpacing income — Bank of America 2025
- Adults with less than $5,000 in savings report over twice the odds of depression and anxiety — savings buffer matters more than monthly income for anxiety outcomes
- The amygdala processes financial threats through the same neural circuitry as physical danger — producing genuine physiological responses to financial information
- Tunneling — the cognitive narrowing produced by scarcity — impairs the prefrontal cortex function needed for sound financial decision-making
- Allostatic load from chronic financial stress produces measurable cardiovascular, immune, sleep, and metabolic consequences
- 60% of financially stressed Americans avoid mental healthcare because of cost — the stressflation paradox
- The most effective financial anxiety interventions address nervous system regulation first — then financial planning
- Financial trauma from childhood leaves lasting neurological imprints that professional therapy addresses most effectively
- Free financial counselling is available in all four Tier 1 countries — combining it with mental health support produces the most complete outcomes
A Word From mindnesto
At mindnesto, we want to say something directly to everyone reading this who feels shame about their financial anxiety. The shame is one of the cruelest features of this experience — because financial anxiety already depletes the cognitive and emotional resources needed to address the underlying situation, and shame depletes them further.
You are not failing. You are not uniquely bad with money. You are experiencing a biologically grounded, statistically normal response to an economic environment that is genuinely more stressful in 2026 than it has been for decades. That does not make the anxiety less real. But it does make it less personal — and less permanent.
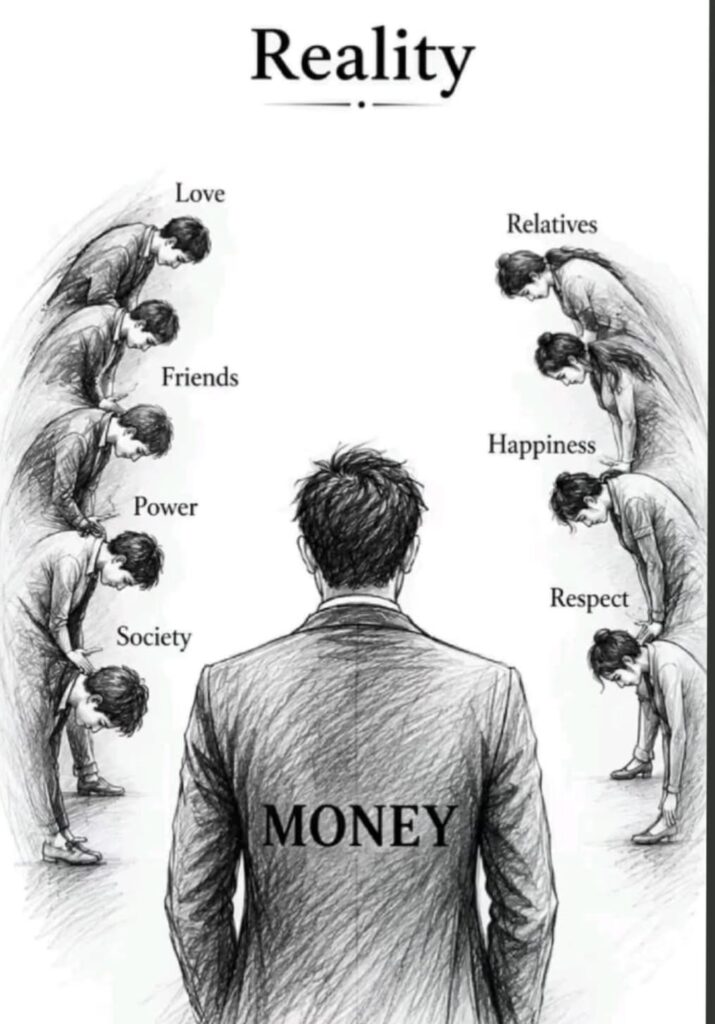
The connection between money and mental health is one of the most important and most underserved conversations in wellbeing. Understanding that money is not simply a financial issue but a neurological one — that it activates threat systems, impairs decision-making, disrupts sleep, and damages physical health — changes how we approach both the money and the mind.
You deserve support with both. 💙
→ Read next: Can Money Buy Happiness? What the 2026 Science Actually Says
→ Also read: Stress Management — The Complete 2026 Guide
Frequently Asked Questions
What is financial anxiety?
Financial anxiety is a persistent pattern of excessive worry, fear, and avoidance centred on money — including income, spending, debt, and financial security. It is not simply concern about a genuine financial difficulty.
Can financial stress cause depression?
Yes — through several specific mechanisms. Financial stress forces withdrawal from the activities, social events, and self-care routines that protect mood — removing the buffers that normally guard against depression.
What is money dysmorphia?
Money dysmorphia is a pattern in which a person’s perception of their financial situation is significantly distorted relative to their actual circumstances — producing persistent financial anxiety or insecurity despite objective financial stability. It affects 29% of Americans overall, rising to 43% of Gen Z and 41% of millennials, and 95% of those who experience it say it negatively impacts their financial behaviour — holding them back from saving or pushing them toward unnecessary debt.
How does financial stress affect the brain?
Financial stress activates the amygdala’s threat response — the same neural circuitry that processes physical danger — producing cortisol elevation, sympathetic nervous system activation, and the tunneling effect described by Harvard’s Sendhil Mullainathan.
What is the best way to manage financial anxiety?
The most evidence-based approach to financial anxiety combines nervous system regulation before financial engagement, scheduled and time-limited financial check-in windows, graduated exposure to avoided financial information, and cognitive reappraisal of financial catastrophising. For financial anxiety with a trauma component — rooted in childhood financial experiences — professional CBT or EMDR produces the most complete outcomes. Free financial counselling from MoneyHelper (UK), NFCC (USA), or National Debt Helpline (Australia) addresses the practical dimension alongside psychological intervention.
When should I seek professional help for financial anxiety?
Seek professional support when financial anxiety has persisted for more than four to six weeks without improvement, when it is significantly affecting your sleep, relationships, or ability to work, when it produces physical symptoms including chest tightness, nausea, or panic attacks, when it involves significant avoidance of financial responsibilities that is worsening your situation, or when it co-occurs with depression or generalised anxiety. In the UK, NHS Talking Therapies provides free self-referral. In the USA, the SAMHSA helpline at 1-800-662-4357 is free and available 24 hours.
Sources and External References
- LifeStance Health — 4 in 5 Americans Report Financial Stress, July 2026
- HealthDataConsortium — Financial Stress Health Effects 2026
- Frontiers in Public Health — Money and Mental Health Scoping Review, July 2026
- Embodied Wellness — Financial Anxiety and the Nervous System, May 2026
- Forward Counseling — The Scarcity Loop 2026
- PMC — Financial Assets and Depression/Anxiety 2024
- APA — Stress in America 2024
- NHS — Money and Mental Health
- Mind UK — Money and Mental Health
- MoneyHelper UK
- StepChange Debt Charity UK
- Citizens Advice UK
- NFCC USA
- CFPB Consumer Finance
- National Debt Helpline Australia
- NHS Talking Therapies
- ADAA — Find a Therapist
- CAMH Canada
- Beyond Blue Australia
- SAMHSA USA